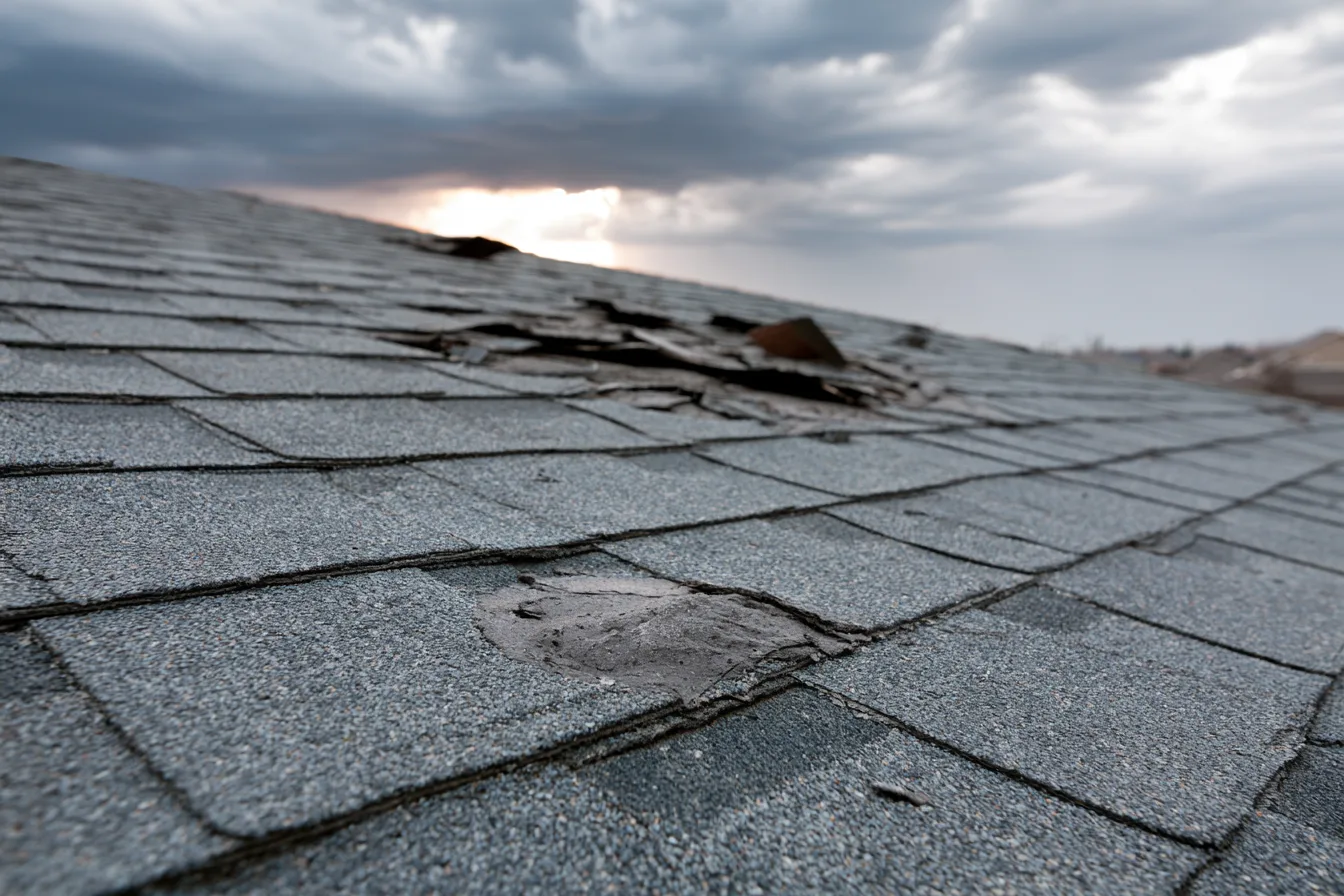
Roof Insurance in Texas
Understand the roof work, the deductible and the policy payment as separate parts of the same decision.
Separate the roof repair from the claim payment
After roof damage, it is easy for the repair decision and the claim payment to become one confusing conversation. Separate them early: first, what work does the roof need; second, what does the policy pay toward that work?
Hurst Roofing Experts can inspect the roof and discuss a practical repair or replacement scope. This guide uses Texas Department of Insurance information to explain common payment terms and the distinct role of your insurer.
A roof repair and a covered loss are different questions
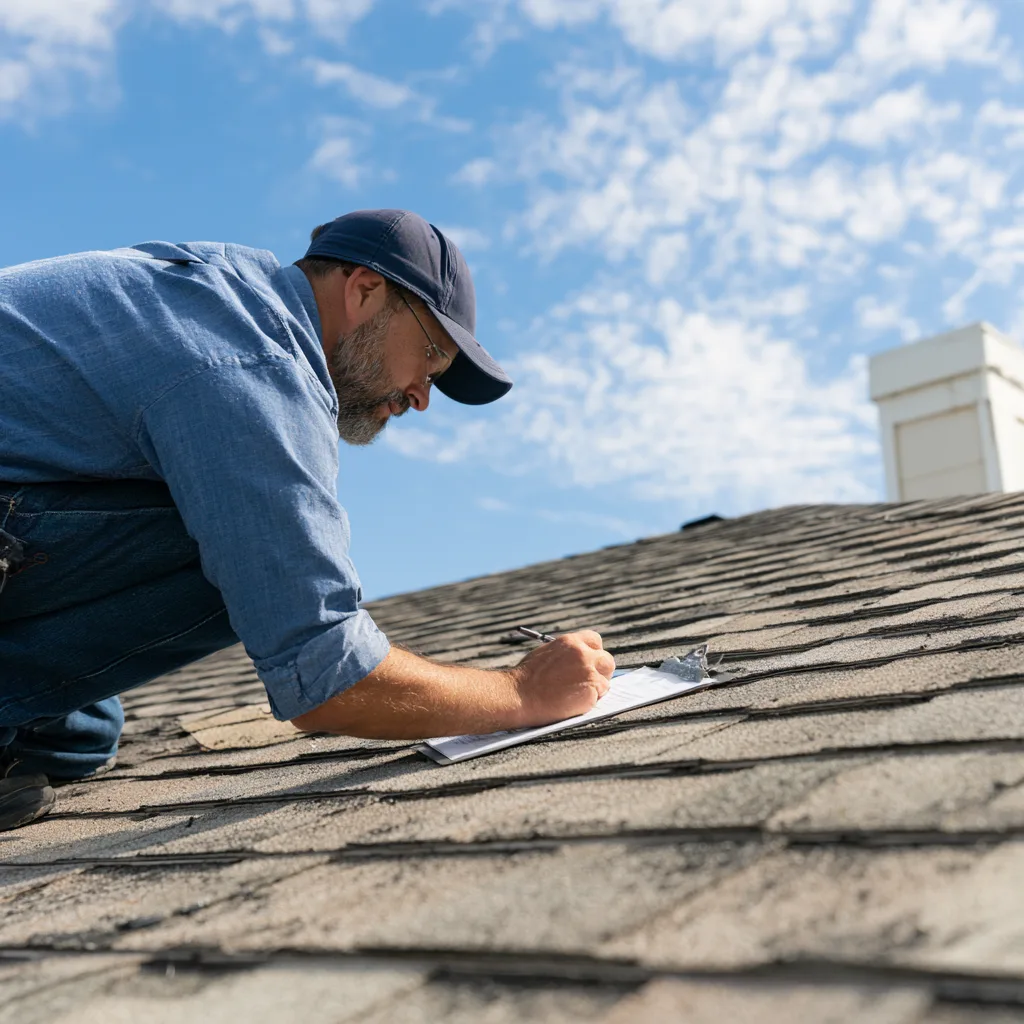
A roof can need work whether or not an insurance policy pays for it. The Texas Department of Insurance roof guidance explains that coverage depends on the policy and the cause of damage. An inspection establishes roofing conditions; the insurer makes the coverage decision.
No visible ceiling leak does not establish that a roof is undamaged. It also does not establish that a claim will be covered. Roof condition and policy terms both need their own assessment.
Deductible, depreciation and payment terms affect the bill
The amount required to complete the roofing work and the amount paid by an insurer may differ. The deductible, valuation terms, limits and excluded work can all affect the owner’s share.
- Replacement cost and actual cash value
Replacement-cost coverage and actual-cash-value coverage value a loss differently. Actual cash value takes depreciation into account. Some replacement-cost claims begin with a payment reduced for depreciation and release an eligible balance after repair requirements are met; the policy and insurer’s instructions control that process.
- The deductible remains the owner’s responsibility
A covered loss does not mean a free roof. TDI explains that a contractor cannot waive or absorb a required deductible, including through misleading rebates or billing. The proposal should describe the construction price clearly.
- Keep excluded work and changes visible
An upgrade, unrelated deterioration or work beyond the covered loss may remain payable by the owner. If removal reveals additional damage, document the actual condition and discuss the roofing change. A request for additional insurance payment is not approval until the insurer decides it.
Keep inspection findings and policy decisions in their roles
The useful division of work is straightforward: we explain the roof condition and construction scope; your insurer explains the policy, claim decision and payment requirements.
Protect people and limit further damage
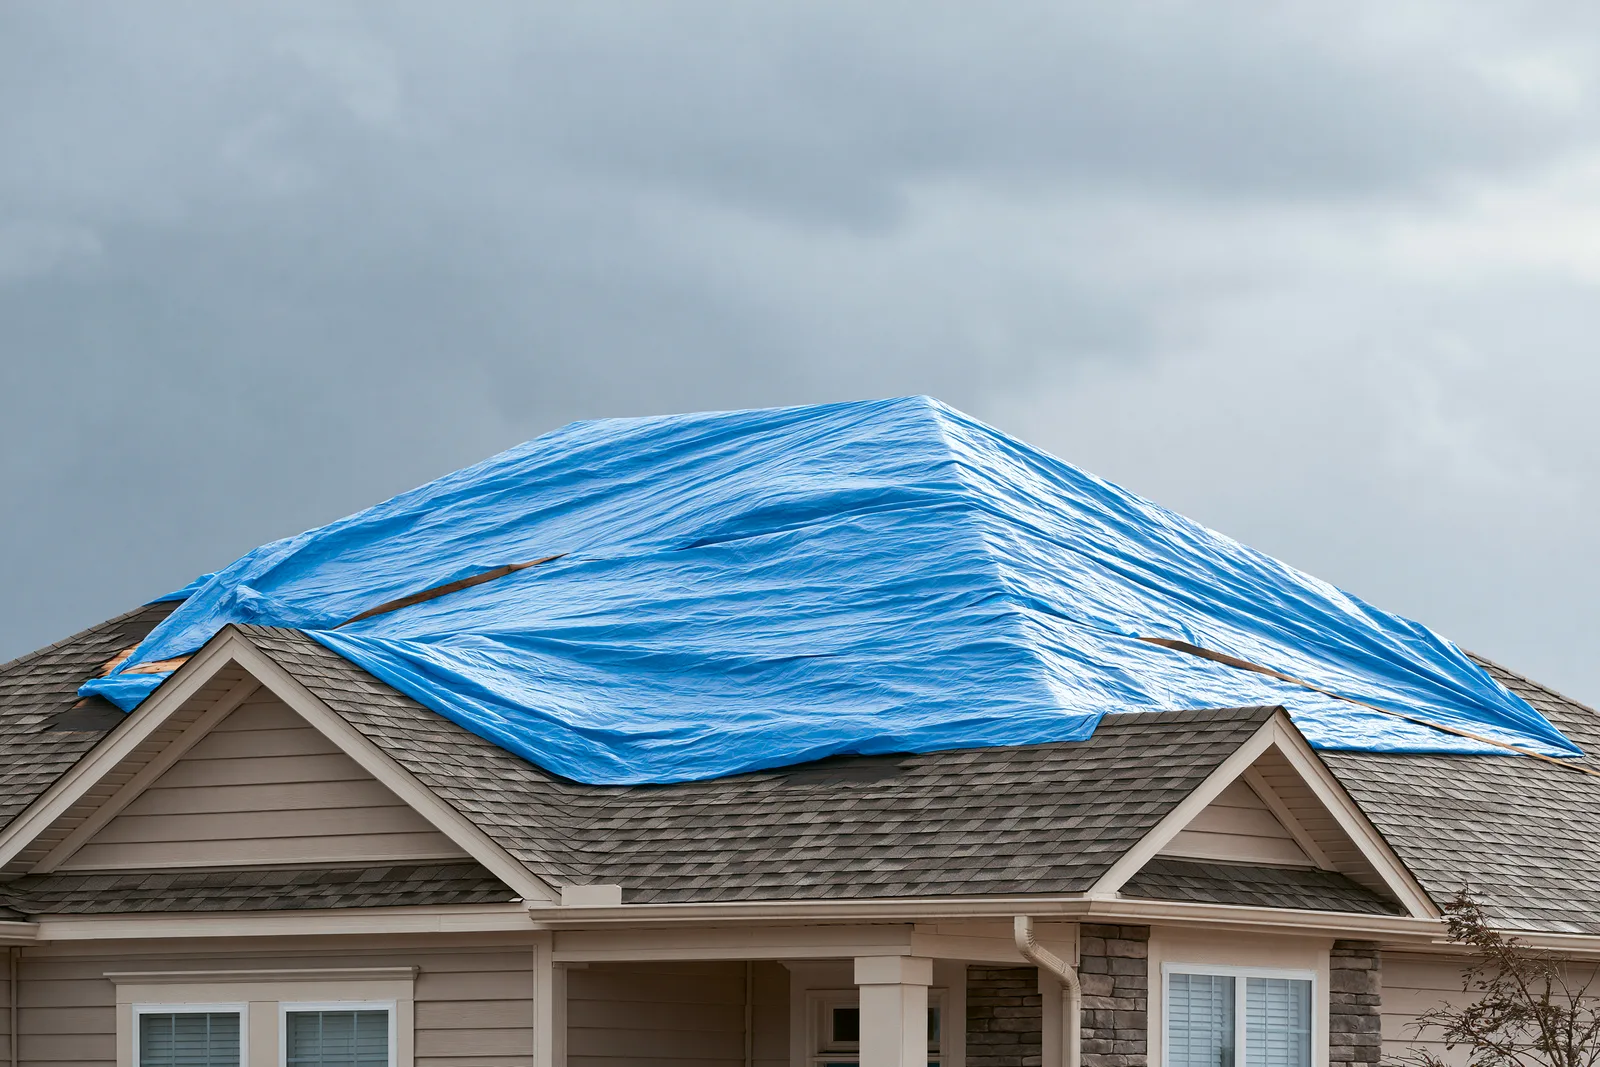
Stay clear of unstable ceilings, wet electrical equipment and damaged roof areas. Temporary protection is a roofing task when conditions allow safe access. TDI’s claim guidance recommends safe documentation, prompt reporting and keeping records of temporary repairs.
Describe the roof work
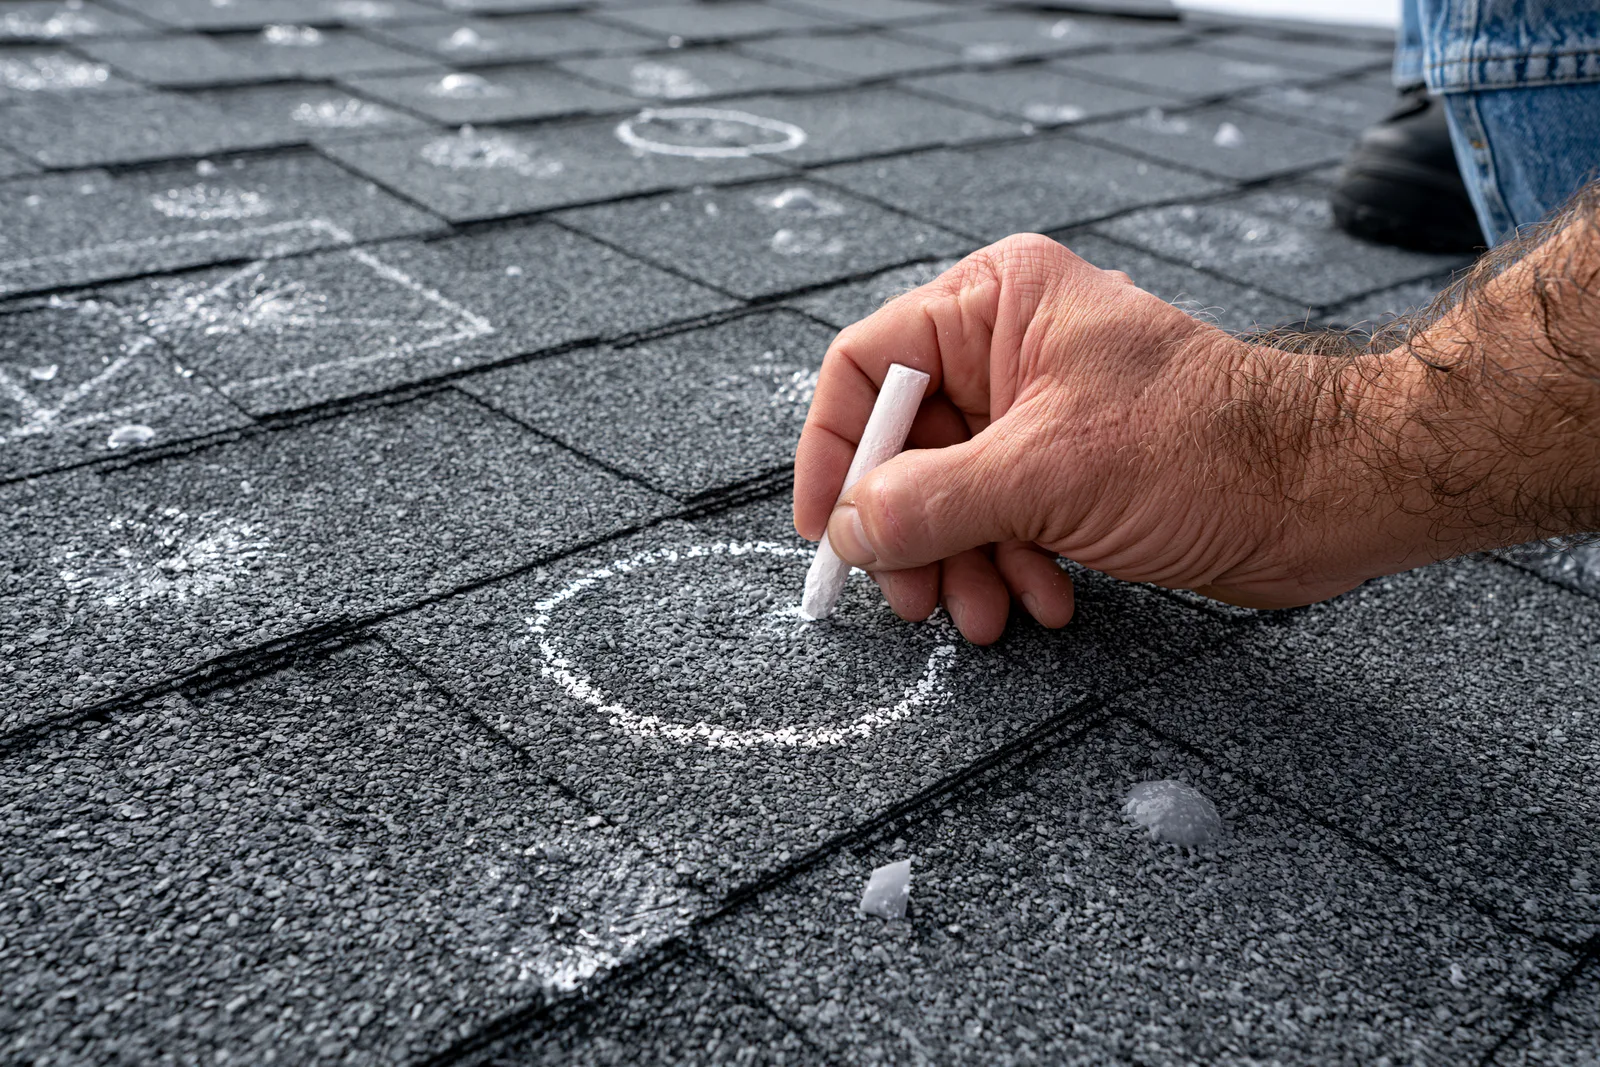
An inspection can identify damaged areas, repairability and the details a lasting repair needs. Keep the proposed work specific to the roof condition. A roofing estimate is not a policy interpretation or a guarantee that every item will be paid.
Coordinate approved construction and records
Agree the construction scope, payment arrangements and any changes with the party authorized to approve the work. Keep the project records relevant to the insurer’s stated requirements. If new damage is uncovered, separate the necessary work decision from the insurer’s response to additional information.
Roof insurance FAQs
Can damage be covered before the roof leaks?
Yes, a covered type of damage can exist before water reaches the interior. The cause, extent and policy terms still determine the insurer’s decision. A storm damage inspection helps establish the roofing condition without promising claim approval.
Is ordinary wear covered?
Ordinary wear and maintenance are generally not covered as a sudden insured loss. An older roof can also sustain new damage, so the actual cause and policy need to be considered. Age alone neither approves nor rejects a particular claim.
How does the deductible affect the payment?
The deductible is the portion of a covered loss the policy makes your responsibility. Other limits, depreciation and excluded work can affect the final owner cost as well. Your insurer can explain how those terms apply to your claim; the roofing agreement should show the actual construction price.
Does a roof inspection determine coverage?
No. A roof inspection explains observable condition and the work it supports. The insurer determines coverage under the policy. If additional damage appears during removal, it can be documented and submitted for consideration without treating additional payment as guaranteed.
Start with the roof condition.
Request a free inspection to understand the damage and the work it needs. Keep the policy and payment questions with your insurer.